
IGA Capital Weekly Macro Update
"Ahead of this week’s Federal Reserve meeting, the IGA Capital team has compiled key market insights and annotated charts to address the primary questions surrounding interest rates, market volatility, and Fed policy expectations."
Treasury & Rates Market
Treasuries staged one of their strongest weekly rallies of 2026. Driven by flight-to-safety buying amid an AI-related stock sell-off, financial turmoil in France, and broader growth concerns, US government debt became a primary haven. The 10-year yield fell 15 bps on the week to close below 5.00% for the first time since September.
Yield Breakdown
2-Year Treasury: Closed down 9 bps to 4.69%
10-Year Treasury: Closed down 15 bps to 4.99% (reached an intraday low of 4.94% on Thursday, its largest single-day drop since August 2024)
30-Year Treasury: Closed down 15 bps to 5.33%
2s10s Curve: Tightened by 6 bps as long-end Treasuries outperformed

Options markets are positioning for potential further yield declines, targeting 4.7% by next week and 4.6% within a month. Fixed income strategists note that haven demand currently outweighs inflation concerns, with elevated coupon buffers enhancing bond appeal relative to volatile risk assets. Capital flows also favored US debt over French peers, pushing 10-year US Treasury yields below French equivalents for the first time since 2013.
Economy & Markets
Equities & Tech Sector
S&P 500: Down 0.9% on the week
Nasdaq 100: Down 2.0% on the week
Dow Jones Industrial Average: Expanded its October lead over the Nasdaq to over 6% as investors rotated into defensive sectors
Re-evaluation of AI infrastructure investments triggered sharp tech declines. Meta’s elevated 2026 capital expenditure outlook ($135–145B) and Lam Research’s below-consensus Q2 guidance contributed to a 7%+ single-day drop in the Philadelphia Semiconductor Index. Neocloud developer Elice Inc. fell 32% on its Seoul debut, adding to broader sector weakness. Citadel’s Ken Griffin noted at the Future of Global Markets Conference that investors are "almost certainly" in an AI bubble.
Commodities & Geopolitics
Brent Crude: Rose over 6% to $117/bbl following escalating conflict in the Strait of Hormuz.
Escalations included IRGC strikes on four US-linked oil tankers, naval mines affecting transit routes, threats toward regional US military facilities, the evacuation of Saudi Aramco's Dhahran headquarters, ordered departures of diplomatic families from Saudi Arabia, and a coastal oil spill in the UAE.
Federal Reserve & Monetary Policy
The market widely anticipates a rate hold at the October 28 FOMC meeting:
October 28 FOMC Meeting: Fed funds futures price a 9.4% probability of a 25bp hike, signaling near-certainty of inaction.
December 9 FOMC Meeting: Implied probability of a 25bp hike stands at 75.4%.
Economic & Policy Context
The Fed has been in a blackout period since October 17. Pre-blackout remarks from SF Fed President Daly noted that rate hikes may be necessary but are not urgent, citing balanced labor market risks. The MOVE Index has traded above 100 for 15 of the last 18 sessions, reflecting reduced forward guidance from Chair Warsh.

Recent economic data presents mixed policy signals:
Labor & Growth: Weekly jobless claims fell to a three-month low of 194k, while the St. Louis Fed GDP nowcast estimated Q3 growth at 3.19%.
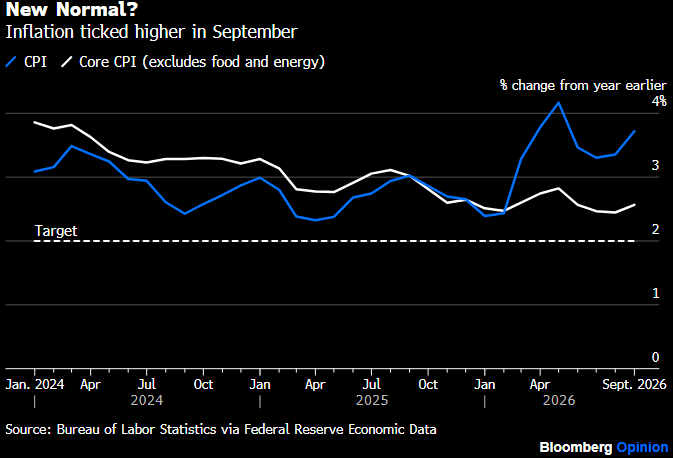
Inflation Pressures: September CPI re-accelerated, the October PMI selling-prices subindex reached a four-year high, and financial conditions tightened following the September hike.
Implied Fed Funds Rates
Current Implied Overnight Rate: 3.881%
October 28, 2026 Meeting: 3.908%
December 9, 2026 Meeting: 4.103%
June 9, 2027 Meeting: 4.510%
December 8, 2027 Meeting: 4.561%
Economic Calendar & Key Events
Calendar Overview
Monday (10/26): No material releases
Tuesday (10/27): Durable Goods, Consumer Confidence, New Home Sales, 5-Year Treasury Auction
Wednesday (10/28): Wholesale Inventories, FOMC Rate Decision & Press Conference
Thursday (10/29): Personal Income, Personal Spending, PCE Inflation (Sept.), Q3 GDP, Initial Jobless Claims, 7-Year Treasury Auction
Friday (10/30): No material releases

Upcoming Focus Areas
Key upcoming data and policy drivers include S&P Global and ISM Manufacturing/Services PMIs, JOLTS, ADP Payrolls, Nonfarm Payrolls, the U.S. Midterm Elections (Nov 3), and the Treasury Quarterly Refunding Announcement (Nov 4).
Please reach out via the contact information below to discuss financing options or specific loan requirements.


Comments