
IGA Weekly Macro Update
Oct 13th, 2026
Equity Divergence: S&P 500 rose 0.5% to hit a fresh all-time high, while the Nasdaq 100 fell 0.6% and the Russell 2000 dropped 1.4%.
Rates & Treasuries: Yields retrenched off multi-decade highs late in the week following strong 10-year and 30-year auctions, with the 10-year settling at 5.24% and the 30-year at 5.60%.
Federal Reserve: September FOMC minutes revealed unanimous backing for the September rate hike and an expectation for another increase by year-end, though market-implied odds for an October hike sit at 17%.
Energy Logistics: Tanker attacks in the Strait of Hormuz spiked to nine in the first week of October, driving supertanker hire costs to $77MM per voyage for US-to-Asia routes.
Economy & Equity Markets
The S&P 500 posted a 0.5% gain on the week to hit a fresh all-time high, absorbing hawkish FOMC minutes, tanker attacks in the Strait of Hormuz, and benchmark yields pushing to levels not seen in over two decades. Other major indices faced pressure, with the Nasdaq 100 falling 0.6% and the Russell 2000 dropping 1.4% as small-cap equities absorbed elevated borrowing costs that briefly pushed the 10-year yield above 5.30% and the 30-year yield to fresh 24-year highs.

Mid-week pressure in chipmakers intensified following a report indicating OpenAI is on track to generate annualized revenue of roughly $50BN—below recent reports suggesting nearly $70BN—raising market scrutiny regarding the sustainability of current AI capital expenditure levels amidst rising capital costs. Risk assets stabilized into the weekend, supported by a partial pullback in crude oil and news that Donald Trump postponed potential attacks on Iran until after the midterm elections. The VIX closed at 14.8, signaling that options markets continue to price in relatively modest near-term equity risk.
Energy & Shipping Infrastructure
Iran increased the frequency of tanker attacks in the Strait of Hormuz. UK Maritime Trade Operations reported nine attacks in the waterway during the first week of October alone—half the total reported across all of September—even as oil shipments through the chokepoint have approached prewar levels in recent weeks.
Freight Costs: Supertanker charter rates reached $77MM per voyage to transport US crude to Asia, compared to a 2025 average of $9.2MM.
Industry Stance: Leadership at the Energy Intelligence Forum noted a diminishing availability of stopgaps to manage ongoing disruptions.
Structural Adjustments: Saudi Arabia is in discussions with counterparties to formalize long-term supply contracts for oil loadings outside the Strait of Hormuz.
Treasury Yields & Fixed Income
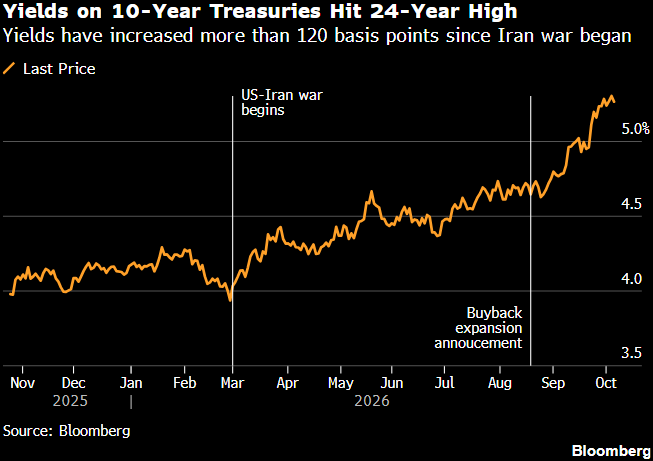
Treasuries experienced early-week selling before two long-end auctions and geopolitical headlines pulled yields off peak levels. The curve steepened early as 30-year yields reached 24-year highs while front-end yields held steady. The 10-year opened the week at 5.31% (peaking at 5.36% on Wednesday) and the 30-year opened at 5.67%, driven by duration supply, European sovereign debt spillovers, and fiscal supply considerations.


Following strong demand for the 10-year auction (awarded at its highest yield since November 2000) and the subsequent 30-year auction, long-end yields declined across two sessions, triggering a bull flattening move. By week's end, the 10-year settled at 5.24% and the 30-year at 5.60%.
Intraweek Treasury Yield Movements
  10-Year: 5.31% (Open) ──► 5.36% (Peak) ──► 5.24% (Close)
  30-Year: 5.67% (Open) ──► 24-Yr Highs  ──► 5.60% (Close)
Institutional Demand: BNY iFlow data showed consistent Treasury inflows through most of Q3 across maturities up to 10 years, with pension funds and insurers adding over $30BN in long-end Treasuries while reducing IG credit exposure by more than $90BN.
Investor Positioning: Bank of America's sentiment survey indicated client duration exposure increased, with long positions on rates representing a high-conviction trade for the remainder of 2026.
Analyst Commentary: Deutsche Bank's George Saravelos noted that negative bond sentiment may be overextended, citing potential risks in the AI ecosystem (disappointing revenue, failed IPOs, or safety events) as potential bond-positive catalysts.
Refunding Expectations: Citi projects that Treasury official Bessent will reduce 20-year and 30-year auction sizes by $3BN each at the November quarterly refunding, funded via increased T-bill issuance.
Federal Reserve & Monetary Policy
The September FOMC minutes confirmed that all 19 officials backed the September rate hike unanimously, with a majority judging that another increase would likely be appropriate by year-end due to insufficient inflation progress and potential tariff risks. The minutes did not outline an explicit timeline for an October hike, aligning with Chair Warsh's data-dependent framework. Following recent labor data showing a +29k September payrolls print, market expectations for an October rate increase stand at 17%.
Fed Speaker Highlights & Policy Outlook
Fed Governor Waller: Stated further hikes will likely be needed but emphasized timing flexibility without requiring tightening at consecutive meetings.
St. Louis Fed President Musalem: Signaled interest rates should rise over the next six-to-nine months to return inflation to target, without explicitly endorsing an October move.
Vice Chair Bowman: Noted no current urgent need for immediate action, calling for additional time to evaluate underlying economic trends.
Political Commentary: Donald Trump stated Warsh should have voted against the September rate hike, while adding he wants Warsh to "vote the way he wants."
Wednesday's upcoming September CPI report represents the final major inflation reading before the October 28–29 FOMC meeting.

FOMC Meeting / Horizon | Implied Fed Funds Rate |
Implied Overnight Rate | 3.879% |
October 28, 2026 | 3.927% |
December 9, 2026 | 4.130% |
June 9, 2027 | 4.604% |
December 8, 2027 | 4.678% |
Economic & Earnings Calendar

Q3 Data Release Schedule – This Week
Monday (10/12): Bond Market Closed (Columbus Day)
Tuesday (10/13): NFIB Small Business Optimism; Existing Home Sales
Wednesday (10/14): CPI (Sept.)
Thursday (10/15): Retail Sales; Empire Manufacturing; Initial Jobless Claims; PPI (Sept.)
Friday (10/16): Industrial Production
Next Week Overview
Housing Starts & Building Permits
20-Year U.S. Treasury Auction
Initial Jobless Claims
S&P Global US Manufacturing PMI & Services PMI
University of Michigan Sentiment
If you have any questions or would like to discuss a loan request, please reach out using the contact information below. info@iga.capital


Comments