
WEEKLY MACRO IGA Capital
1. Executive & Economic Overview
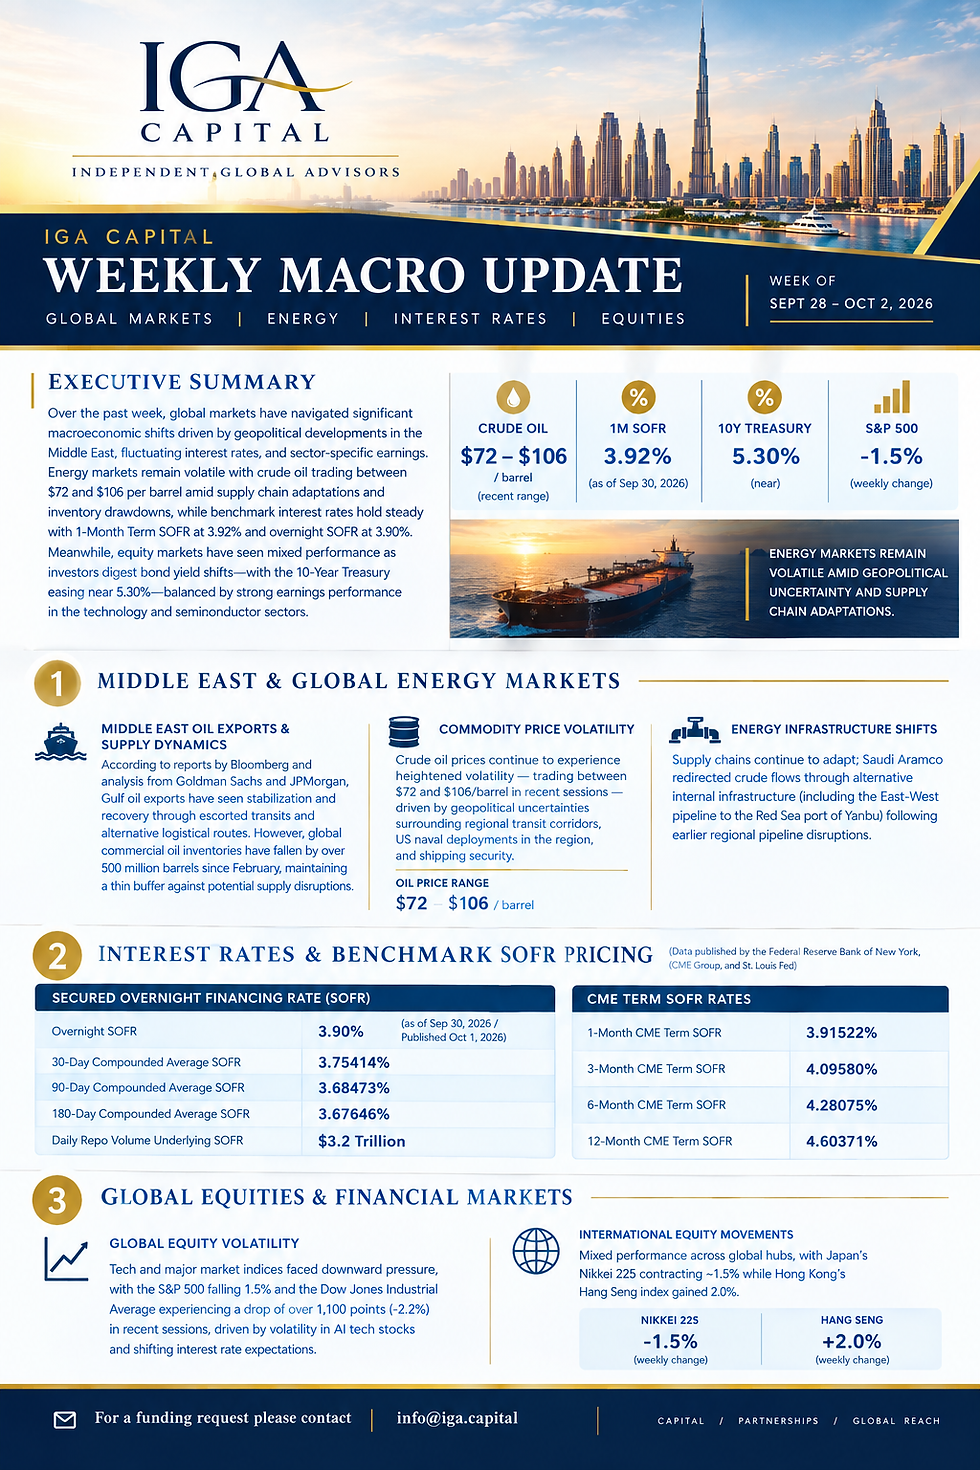
U.S. equity markets closed the week in positive territory, with the S&P 500 rising 0.5% and the Nasdaq 100 gaining 1.8%. Both benchmarks traded lower for the majority of the week before Friday’s nonfarm payrolls release shifted sentiment.
Labor Market & Monetary Expectations: September payrolls increased by 29k against a Wall Street consensus estimate of 90k, while the unemployment rate edged up to 4.2%. The payrolls print undershot the most pessimistic Wall Street forecast, sending the Nasdaq to a record high as markets priced down near-term rate hike expectations and Micron’s financial results confirmed ongoing demand in the AI cycle. Swap markets reduced the probability of an October Federal Reserve rate hike from 40% down to 20% by the end of the week.

Geopolitical & Commodity Pressures: The trading week opened with broad cross-asset selling following President Trump’s rejection of Iran’s seven-day ceasefire proposal. Brent crude spiked toward $107/bbl, and 10-year Treasury yields rose nearly 10 bps to a 24-year high, with rate-sensitive sectors underperforming and the Russell 2000 leading losses.
Supply Chain & Energy Dynamics: Tehran maintained its conditions regarding the Strait of Hormuz, while reports indicated Iran’s operational control over the waterway is deteriorating. US Naval forces and regional Gulf producers demonstrated enhanced defense capabilities against attacks, and Iran recorded zero crude tanker loadings in September under a US naval blockade. Following repairs to drone strike damage on Saudi Arabia’s East-West pipeline, Middle East crude exports recovered via alternative routes—remaining below prewar levels but easing Brent crude off its intra-week peaks.
Macro Backdrop: Elevated oil prices, unresolved conditions around the Strait of Hormuz, and consumer confidence reaching a 12-year low frame the macroeconomic environment five weeks ahead of the U.S. midterm elections.
2. Federal Reserve & Monetary Policy
A coordinated shift in tone from key Federal Open Market Committee (FOMC) members altered market expectations regarding the near-term path of interest rates prior to Friday’s labor data.

Fedspeak Alignment: Fed Vice Chair Jefferson and New York Fed President Williams signaled in separate appearances that the Committee has time to evaluate incoming data before implementing additional rate increases. President Williams explicitly noted that while one more hike "late this year" may be appropriate, there is "no urgency to act" following the September adjustment, shifting market focus away from October toward December. Vice Chair Jefferson highlighted that while inflation has remained elevated, careful assessment of incoming data is required.
Additional Fed Commentary: Minneapolis Fed President Kashkari stated that the Fed will take necessary steps to return inflation to target without offering a specific timeline. Fed Governor Barr and Philadelphia Fed President Paulson noted that modest further tightening may be warranted if economic conditions evolve as projected.
Market Pricing: Following Friday’s payroll release, swap markets priced a ~20% probability of a rate hike at the October 28 FOMC meeting, positioning December as the base case for the next potential increase, with expectations of potential tightening extending into 2027.
Structural Considerations: Factors influencing the policy outlook include the upcoming midterm elections on November 4, uncertainty surrounding the neutral interest rate during an oil-price shock, and tighter financial conditions resulting from higher long-end Treasury yields.
Implied Fed Funds Rates (Market Pricing)
Current Implied Overnight Rate: 3.876%
October 28, 2026 Meeting: 3.927%
December 9, 2026 Meeting (Year-End): 4.118%
June 9, 2027 Meeting (Mid-Year): 4.578%
December 8, 2027 Meeting (Year-End): 4.661%
3. Treasury Market & Fixed Income
Fixed income markets experienced continued selling pressure across the curve last week, driven by oil-related inflation concerns, growth resilience, ongoing fiscal supply, and corporate issuance, including Paramount’s $30 billion eight-part offering.
Yield Benchmark Movements: The 10-year U.S. Treasury yield reached a 24-year high of 5.34%, while the 30-year yield crossed 5.63% for the first time since 2002. Over the preceding quarter, the 10-year yield increased by 87 bps, marking its largest quarterly increase since Q1 1994.

Inflation Read vs. Long-End Demand: Core PCE inflation printed slightly below expectations at 3.0% YoY (vs. 3.3% estimate). Although short-end yields rallied initially, long-end yields reversed, with the 30-year yield rising to 5.58%.
Yield Curve Dynamics: The 2s10s yield curve steepened by 14 bps on the week as expectations for an October rate hike were scaled back, pulling short-end yields lower while long-end yields continued to push higher. The 2s10s spread is currently trading near its two-year average of 43 bps after hitting a seven-month flat point in September.
Global Context: Treasury Secretary Bessent noted that the yield movement aligns with broader global trends rather than isolated U.S. factors, citing developments such as the UK 30-year gilt yield crossing 6% for the first time since 1998.

4. Economic Calendar
This Week (Week of October 5)
Monday, Oct 5: S&P Global US Services PMI; ISM Services
Tuesday, Oct 6: Trade Balance; 3-Year U.S. Treasury Auction
Wednesday, Oct 7: 10-Year U.S. Treasury Auction; FOMC Meeting Minutes
Thursday, Oct 8: Initial Jobless Claims; 30-Year U.S. Treasury Auction
Friday, Oct 9: University of Michigan Consumer Sentiment Index

Next Week
Monday: Columbus Day (U.S. Financial Markets Closed)
Weekly Data Releases: NFIB Small Business Optimism; Consumer Price Index (CPI); Retail Sales; Initial Jobless Claims; Producer Price Index (PPI); Industrial Production
If you have any questions or would like to discuss a loan request, please reach out using the contact information below. info@iga.capital


Comments